


7 listopadových knižních novinek: romance, magie i skutečné zločiny
Listopad si přímo říká o večery strávené s knihou. Venku se brzy...


Kniha ( pevná vazba )


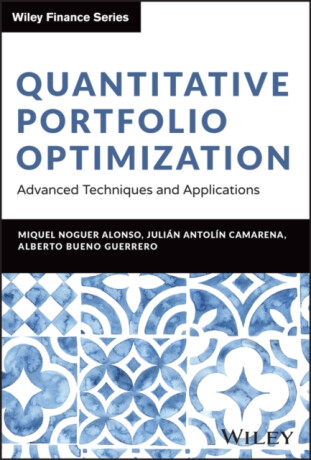
Expert guidance on implementing quantitative portfolio optimization techniques In Quantitative Portfolio Optimization: Theory and Practice, renowned financial practitioner Miquel Noguer, alongside physicists Alberto Bueno Guerrero and Julian Antolin Camarena, who possess excellent knowledge in finance, delve into advanced mathematical… Přejít na celý popis


5.0 z 5 hvězdiček
Voucher


5.0 z 5 hvězdiček
Voucher
Expert guidance on implementing quantitative portfolio optimization techniques
In Quantitative Portfolio Optimization: Theory and Practice, renowned financial practitioner Miquel Noguer, alongside physicists Alberto Bueno Guerrero and Julian Antolin Camarena, who possess excellent knowledge in finance, delve into advanced mathematical techniques for portfolio optimization. The book covers a range of topics including mean-variance optimization, the Black-Litterman Model, risk parity and hierarchical risk parity, factor investing, methods based on moments, and robust optimization as well as machine learning and reinforcement technique. These techniques enable readers to develop a systematic, objective, and repeatable approach to investment decision-making, particularly in complex financial markets.
Readers will gain insights into the associated mathematical models, statistical analyses, and computational algorithms for each method, allowing them to put these techniques into practice and identify the best possible mix of assets to maximize returns while minimizing risk. Topics explored in this book include: Specific drivers of return across asset classes Personal risk tolerance and it#s impact on ideal asses allocation The importance of weekly and monthly variance in the returns of specific securities
Serving as a blueprint for solving portfolio optimization problems, Quantitative Portfolio Optimization: Theory and Practice is an essential resource for finance practitioners and individual investors It helps them stay on the cutting edge of modern portfolio theory and achieve the best returns on investments for themselves, their clients, and their organizations.
0.0 z 5 0 hodnocení čtenářů
0× 5 hvězdiček 0× 4 hvězdičky 0× 3 hvězdičky 0× 2 hvězdičky 0× 1 hvezdička
Získejte přehled o vývoji ceny za posledních 60 dní.
Listopad si přímo říká o večery strávené s knihou. Venku se brzy...
Mezi tvými oblíbenými romány se rozsvítila malá japonská ulička. Má...
Po úspěšných knihách s Erikou Fosterovou a Kate Marshallovou se Robert...
Vánoce jsou za dveřmi a s nimi přichází i každoroční otázka: Co letos...
Další díl podcastu Buď inspirující je tady! Tentokrát naše pozvání...
Vánoce už pomalu klepou na dveře a s nimi přichází i každoroční otázka:...
Říká se, že není důležité vyhrát, ale zúčastnit se. Zkuste to...
V předchozím halloweenském čtení jsme se společně ponořili do umění...
Pro miliony diváků zůstane navždy kapitánem Jeanem-Lucem Picardem ze Star...
Od stydlivého kluka, který miloval sport, až po hlas českého hokeje
Robert Záruba v knize vypráví o své cestě ke komentátorskému mikrofonu i o více než 2000 přenosech.
Mohlo by vás zajímat
Risa chtěla na univerzitě hlavně nevyčnívat
Jenže jako runová čarodějka má k problémům blíž, než by si přála. Když dostane nabídku přidat se k lovcům nadpřirozených bytostí, čeká ji pořádně divoké dobrodružství.
Mohlo by vás zajímat
Aby zachránila svého bratra, nechá se uvěznit
V Endlocku, brutálním vězení kde bohatí loví vězně pro zábavu, však narazí na dozorce, který jí začne být nebezpečně blízký.
Mohlo by vás zajímat
Kdo ví, ten odpoví. Kdo neví, ten riskuje!
Myslíte si, že víte všechno? Desítka vás rychle přesvědčí, že i ta nejchytřejší hlava občas zaváhá! Odpovídejte na otázky, sbírejte body a rozhodněte se, jestli zariskujete, nebo si výhru raději pojistíte.
Mohlo by vás zajímat
Rozkvetlá radost z LEGO® kostek!
Kopretiny, levandule a jedna roztomilá beruška přinášejí pořádnou dávku jarní nálady! S LEGO® Botanicals si postavíte vlastní barevnou kytici, která bude dělat radost po celý rok.
Mohlo by vás zajímat
Dvanáct kapitol plných rodinných dobrodružství!
Kroužky, výlety, oslavy i rodinné povinnosti? S Rodinným plánovacím kalendářem 2027 z dílny Knihy Dobrovský budete mít všechno pěkně pohromadě. A díky kouzelným knižním ilustracím bude každý měsíc o něco čtivější!
Každý měsíc společně přečteme tisíce knih




Tento web je chráněn službou reCAPTCHA a platí pro něj Zásady ochrany soukromí a Smluvní podmínky. | © 2001–2026 DOBROVSKÝ s.r.o. Všechna práva vyhrazena.




 KnihyDobrovsky.cz
 knihydobrovsky
 @knihydobrovskycz
 @knihydobrovsky